

Q1 2026 kept us busy across several fronts. We made two new investments, each tackling a different kind of friction in the broader transition: Dig Energy, making geothermal affordable enough to deploy at scale, and BackChannel, building the infrastructure retail needs to reduce waste and unlock value from excess inventory.
Both are asset-light in different ways. Both are tackling problems that have persisted for long enough that the market stopped expecting a real fix.
The themes we are tracking are converging around a common thread: the transition needs more than clean technology. It needs resilient supply chains, secure energy infrastructure, and serious tools for the climate impacts already underway. We are going deeper on each of these themes and will keep sharing as our thinking sharpens.
💼 New Investments
⚡ Dig Energy
Heating and cooling account for roughly a third of global energy use, and most of that demand still runs on fossil fuels. Ground-source geothermal is one of the best tools to change that: stable, efficient, and resilient year-round. The reason it hasn’t scaled is simple: drilling is too expensive, too slow, and too complex for most commercial projects.
Dig Energy is fixing that. The company has built a compact, purpose-built drilling system for shallow geothermal that reduces the time, cost, and complexity of installation. Its system is designed for real-world sites, repeatable operations, and workflows that do not require highly specialized contractors. Co-founders Dulcie Madden and Thomas Lipoma bring deep technical expertise and a field-first mindset, with an initial focus on commercial facilities and campuses where the economics can stand on their own.
We’re proud to back Dulcie, Thomas, and the team alongside co-investors Avila, Azolla, and Baukunst.
📦 BackChannel
Excess inventory is one of the largest, most overlooked inefficiencies in retail. Traditional liquidation channels are opaque, slow, and hard to control, leaving brands stuck between losing margin and losing brand equity. In textiles alone, 92 million tons of waste are generated each year.
BackChannel is building the structured marketplace this market is missing: a B2B platform in Brazil that connects brands and distributors moving overstock with vetted retailers seeking quality inventory. The business is capital-efficient and disciplined, closing 2025 with R$25M in annualized GMV, 1,000+ active buyers, and positive contribution margins. The founders, Guille Freire and Guille Arslanian, previously built Trocafone, Brazil’s leading refurbished electronics platform. They know secondary markets, and they are building the trust layer that this market has been missing.
💰 Market Notes
The energy transition is running into a different kind of friction: the harder, slower constraints that sit between today’s grid and the one we need. Supply chains cannot keep up, key materials are difficult to source, and infrastructure was not built for the demands now being placed on it.
We’ve been spending time across several of these pressure points.
Critical minerals sit at the center of many of these constraints. The conversation has matured well beyond “we need more lithium.” We’re now tracking the full value chain, from exploration and extraction to processing and recovery, looking at where the real bottlenecks are and where technology can change the economics. The opportunity is large and still underinvested relative to the scale of the problem.
Recent geopolitical volatility has sharpened something that was already becoming clear: energy resilience is a national and economic security issue, not just a climate one. Disruptions to global energy markets are a reminder of how exposed centralized, fossil-fuel-dependent infrastructure remains. Distributed generation, grid hardening, and energy storage are no longer niche bets. Capital and policy attention are increasingly following.
And then there is adaptation. Climate impacts are no longer future scenarios; they are current events, showing up in insurance losses, agricultural disruption, and infrastructure failure. We’re increasingly focused on the technologies addressing this reality head-on, from parametric insurance and early warning systems to resilient energy systems and climate risk analytics. The adaptation market is large, underfunded, and moving fast.
We’re working on deeper dives across each of these themes. If you’re building, investing, or just thinking hard about any of them, we’d love to compare notes.
🌎 Networking
GSB Climate Happy Hour – February
After the Stanford GSB Climate and Innovation Summit, we hosted a casual happy hour to keep the conversations going with founders, investors, and operators across the ecosystem. The GSB brings together business, innovation, and climate in a way few places do, and the energy in the room was a reminder of what makes this community so special.
PDAC – March
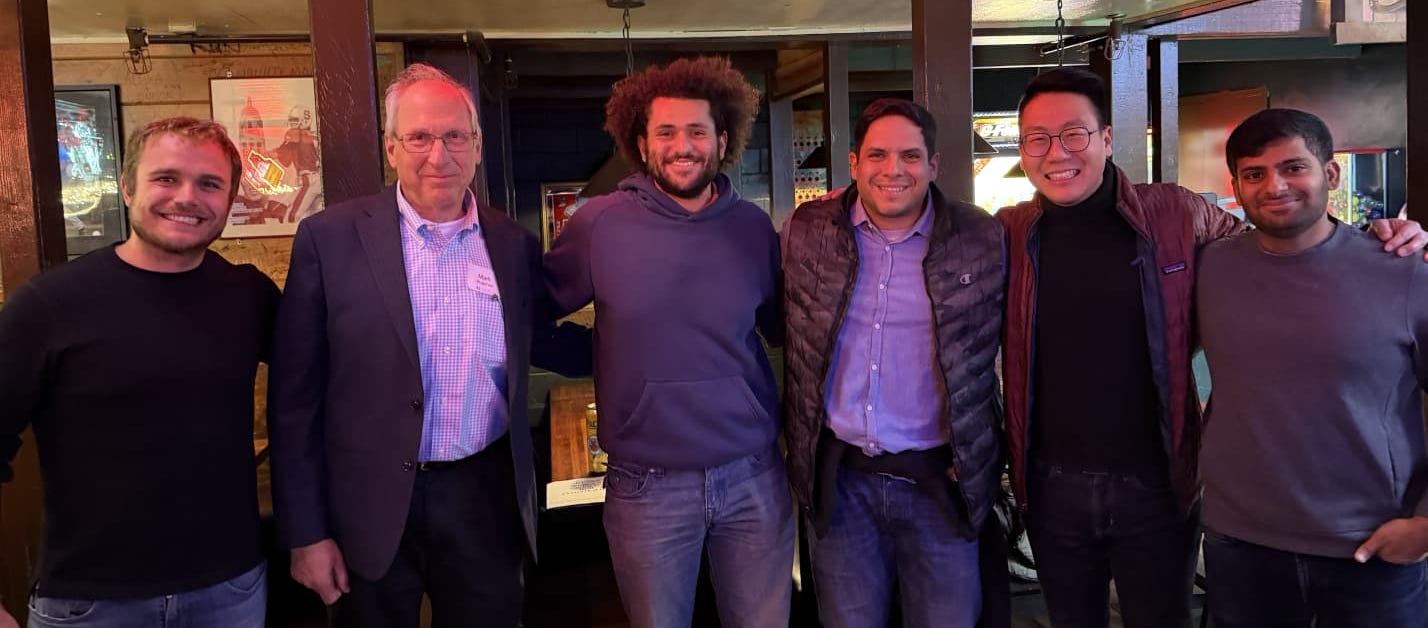
At PDAC in Toronto, the world’s largest mining and mineral exploration conference, we spent time with the upstream dynamics shaping the materials economy, from copper and lithium to the policy and capital flows surrounding them. Critical minerals remain foundational to the energy transition, and staying close to this market continues to sharpen how we think about where technology can unlock supply.
AgroTech Studio Chile – April
Our Associate José Tomás Joglar participated as a speaker at AgroTech Studio, an innovation bootcamp for the next generation of agtech and climate founders in Chile, organized by Reciprocal and UC Davis Chile. JT joined a conversation on impact metrics in the space — a topic that matters a lot at the earliest stages, where founders are still shaping what success looks like. A great initiative building exactly the kind of pipeline we want to see in the region.
VC Latam Summit – April
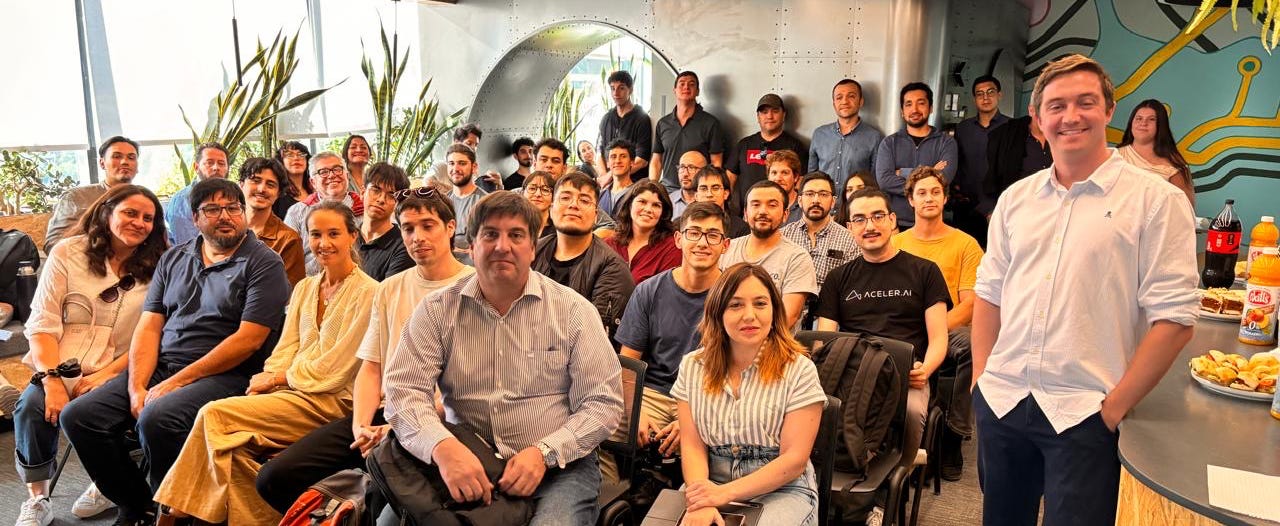
As investors operating across both Latin America and the U.S., staying close to the bridge between the two markets is part of how we work. The VC Latam Summit in Miami is one of the best places to do that: a concentrated gathering of GPs, LPs, and operators tracking where capital is flowing in the region and how the LatAm-U.S. connection is evolving. This year’s conversations reinforced why that corridor matters, and where the next set of opportunities is taking shape.
SF Climate Week – April
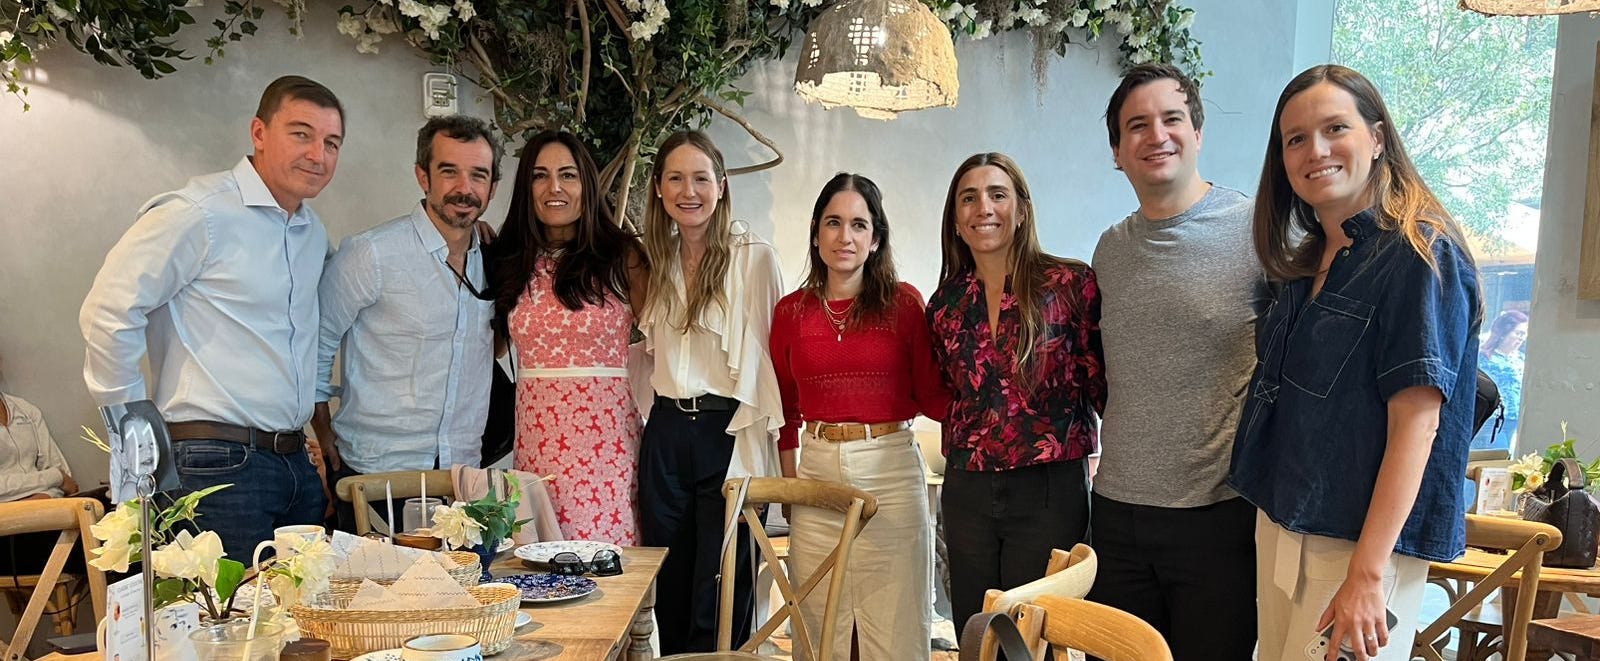
At SF Climate Week, our focus was energy and grid infrastructure, alongside the rise of Physical AI as a category. Across conversations, deployment economics kept surfacing as the defining pressure across industries. The question is no longer only whether these technologies work. It is whether they can be deployed at a price that makes the economics hold.
Climate Happy Hour – April
Before the CREO gathering in London, we co-hosted a climate investor happy hour with RA Capital, bringing together investors and operators to reconnect, compare notes, and continue building relationships across the climate ecosystem.
🔜 Looking Ahead
The second half of 2026 is shaping up to be active. We are continuing to build the portfolio across energy and grid infrastructure, circularity, and critical minerals, while staying close to the founders, turning the transition’s bottlenecks into markets.
Thank you to everyone who has shared ideas, made introductions, and spent time with us this quarter. The conversations and connections are what make this work worthwhile, and we are grateful to be building alongside such a thoughtful community.
More soon,
Sunna Ventures Team